| # | Peril | Usually covered | Watch out for |
|---|---|---|---|
| 1 | Fire or lightning | Kitchen fire, lightning strike and resulting smoke and water from firefighting | Intentional acts; damage to the item that was deliberately heated (a scorched pot) |
| 2 | Windstorm or hail | Shingles torn off, hail-damaged roof, rain entering through that opening | Rain entering without wind or hail damage first creating an opening |
| 3 | Explosion | Gas appliance explosion | Bursting water pipes are handled under other perils |
| 4 | Riot or civil commotion | Damage during a riot | — |
| 5 | Aircraft | Damage from aircraft or objects falling from them | — |
| 6 | Vehicles | A car driving into the house | Some policies exclude damage by a vehicle you own or drive |
| 7 | Smoke | Sudden smoke damage, including from a fireplace malfunction and nearby wildfires | Smoke from agricultural smudging or industrial operations |
| 8 | Vandalism or malicious mischief | Deliberate damage by others | Often excluded if the home was vacant beyond a set period (commonly 60 days) |
| 9 | Theft | Break-in and stolen property | Theft from a vacant home under construction; sublimits for jewelry and cash |
| 10 | Falling objects | A tree limb crashing through the roof | Interior damage generally requires the object to damage the roof or walls first |
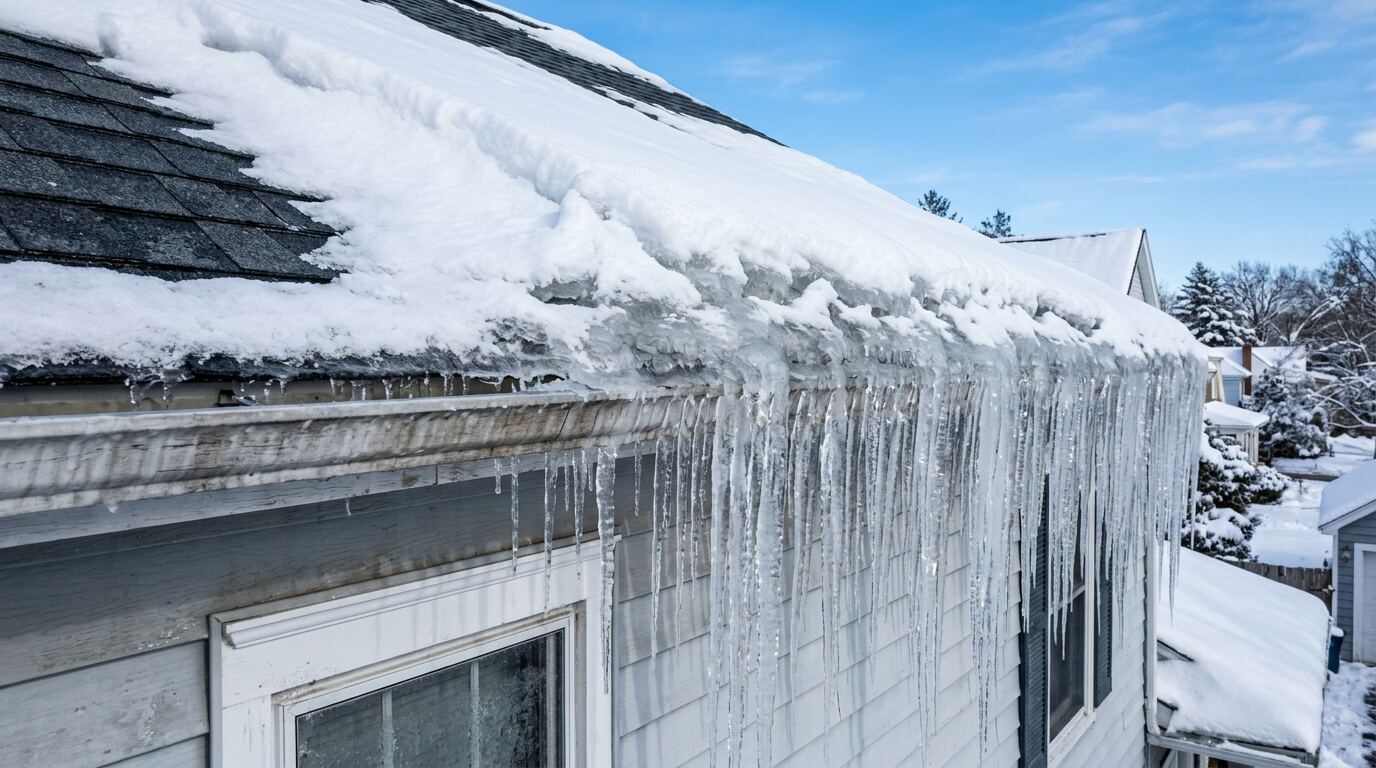
| 11 | Weight of ice, snow or sleet | Roof or porch collapse from snow load | Damage to awnings, fences, patios and pools is often excluded |
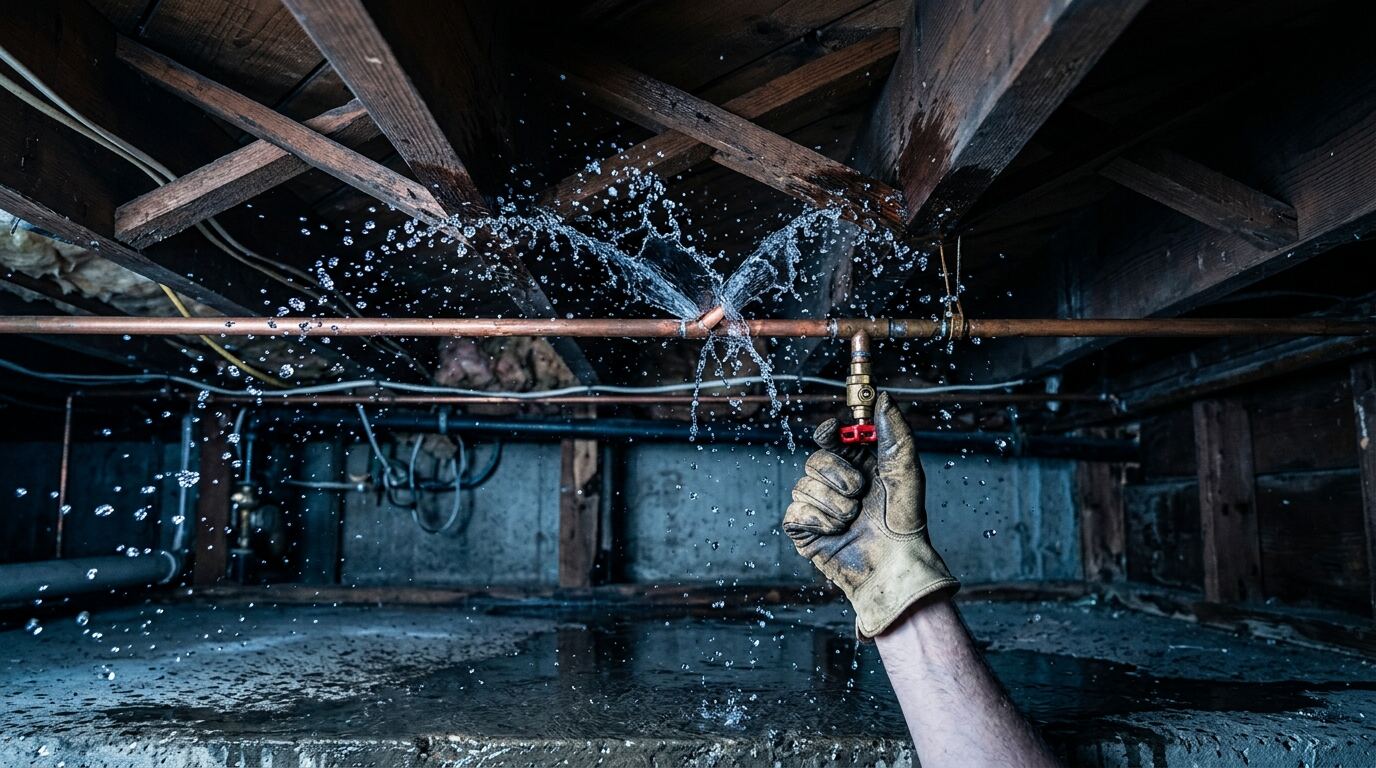
| 12 | Accidental discharge or overflow of water or steam | Burst pipe, water heater failure, washing machine hose split | Continuous or repeated seepage; the failed system itself; freezing in vacant homes |
| 13 | Sudden tearing apart, cracking, burning or bulging | A water heater or steam boiler that suddenly ruptures | Gradual deterioration |
| 14 | Freezing | Frozen pipes and appliances that burst | Not covered if heat wasn’t maintained or water wasn’t shut off and drained in an unoccupied home |
| 15 | Sudden damage from artificial electrical current | A power surge damaging wiring and electronics | Often excludes damage to tubes, transistors and similar components |
| 16 | Volcanic eruption | Damage from eruption, ash and lava flow | Earthquake and land shock waves are excluded |
The perils that matter most for water damage
Most water losses fall under accidental discharge (#12), sudden tearing apart (#13) and freezing (#14). Rain damage usually has to come through a hole made by windstorm or hail (#2) or a falling object (#10). Flood, sewer backup and groundwater aren’t named perils at all — they need separate coverage. See Does insurance cover water damage?
The perils that matter most for fire and smoke
Fire (#1) and smoke (#7) cover the loss itself, the smoke that spreads through the house and the water used to put the fire out. For wildfire smoke, see our wildfire smoke guide.
Want to know which form you have? Read HO-2 vs HO-3 vs HO-5 vs HO-6. Need help with a claim? See insurance claim help.
General information only, based on common policy forms. Your policy’s actual wording, endorsements and state law control coverage.